 Chat With Us


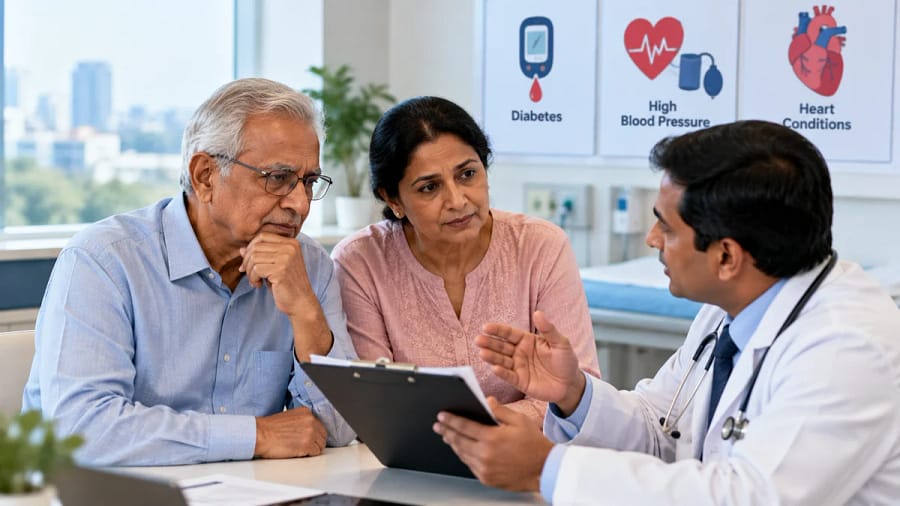
Travelers with multiple pre-existing medical conditions often have an important question when buying visitor insurance: If I have diabetes, high blood pressure, and a heart condition, do I get a separate coverage limit for each condition, or is there one combined limit?
The answer depends on the specific insurance plan and its policy wording. Travelers should not assume that the coverage limit for acute onset of pre-existing conditions automatically applies separately to each medical condition. In many plans, a stated sub-limit may be a combined maximum for eligible treatment related to pre-existing conditions.
For example, if a policy provides a $25,000 maximum for eligible acute onset of pre-existing conditions, you should not automatically assume that you have $25,000 available for diabetes, another $25,000 for hypertension, and another $25,000 for a cardiac condition.
The way the benefit works depends on the plan’s definitions, benefit schedule, exclusions, age requirements, and other terms.
A pre-existing condition generally refers to a medical condition that existed before the insurance coverage began, i.e., before the effective date of the insurance policy.
Depending on the policy, a pre-existing condition may involve a condition that was:
Common examples may include:
The name of a medical condition alone does not determine whether it is covered. It would depend on the policy’s definition and applicable benefit provisions control. Taking medication for an illness on a regular basis is considered a pre-existing condition.
Many visitor insurance plans do not provide broad coverage for ongoing treatment of pre-existing conditions. Instead, some plans offer limited benefits for an acute onset of a pre-existing condition, subject to specific requirements and exclusions.
An acute onset of a pre-existing condition is a specific insurance concept and should not be confused with routine treatment of a chronic condition.
Some visitor insurance plans may provide limited coverage when a pre-existing condition suddenly and unexpectedly becomes symptomatic or requires emergency treatment, subject to the policy’s definition.
For example, a traveler with controlled hypertension may experience a sudden medical event while visiting the United States.
Whether that event qualifies for an acute-onset benefit depends on the policy’s specific definition and requirements. The certificate wordings for each policy will define an acute onset and specify if the acute onset can be covered for a chronic condition or only for a non-chronic condition.
A traveler should therefore avoid assuming that every medical problem involving an existing condition will qualify.
A sub-limit is the maximum amount the policy will pay for a specific covered expense or medical condition, even when the overall policy maximum is higher. Sub-limits are commonly found in fixed benefit plans, but some comprehensive plans may also include sub-limits for specific benefits or conditions. For example:
The $25,000 acute onset of pre-existing condition benefit represents a maximum amount available for eligible expenses related to that benefit, subject to the plan’s terms and conditions. It is usually a sub-limit within the overall $250,000 policy maximum, meaning covered expenses may be paid up to $25,000 rather than the full policy maximum for that specific category.
However, the important question becomes: Is that $25,000 available separately for diabetes, hypertension, and cardiac conditions? Not necessarily. In many plans, the sub-limit is a combined maximum for all eligible acute onset pre-existing condition claims, rather than a separate $25,000 limit for each medical condition.
In most cases, they may.
If a policy states that acute onset of pre-existing conditions is covered up to a single $25,000 maximum, travelers should not assume that the limit automatically multiplies based on the number of medical conditions they have.
For example, consider a traveler with:
If the plan provides a $25,000 maximum for eligible acute-onset pre-existing condition treatment, it should not automatically be interpreted as:
$25,000 + $25,000 + $25,000 = $75,000.
The policy may instead establish one combined maximum for eligible expenses related to pre-existing conditions.
However, insurance plans can structure benefits differently. Some may contain condition-specific provisions, separate benefit limits, or other restrictions.
The only way to determine how multiple conditions are treated is to review the specific policy wording.
Consider a 72-year-old visitor who has:
The traveler purchases a visitor insurance plan with an overall policy maximum of $250,000 and a $25,000 acute-onset pre-existing condition benefit.
During the trip, the traveler develops chest pain and is taken to the emergency room.
The medical evaluation could involve:
The important question is not simply whether the traveler has a $250,000 policy maximum.
The insurer may first need to determine which policy benefit applies to the medical event and whether the expenses qualify under the acute-onset pre-existing condition provision.
If the applicable benefit has a $25,000 maximum, that sub-limit may restrict the amount payable for eligible expenses under that provision.
The actual determination of the claim depends on the policy terms and medical circumstances.
This is where the situation can become more complicated. Consider a traveler with diabetes and hypertension who experiences a cardiac event during the trip.
The medical event may involve several interconnected conditions. The insurer may need to determine whether the treatment is related to:
The classification can affect which benefit and limitation apply.
For example, hospitalization for chest pain could involve diagnostic testing, cardiac treatment, medication, physician services, and emergency care. Whether those expenses fall under general medical benefits, pre-existing condition benefits, or another policy provision depends on the plan.
This is why simply looking at the policy maximum is not enough.
Multiple pre-existing conditions are particularly important for travelers who are older or who regularly take prescription medications. Someone may have several conditions that are stable and well-controlled, such as:
A traveler may feel healthy and have no current symptoms. However, the fact that the conditions are controlled does not necessarily mean they are treated as new conditions under an insurance policy.
The policy’s definition of pre-existing condition and its specific coverage provisions still apply. Travelers should therefore examine the policy before purchasing coverage, rather than waiting until a medical claim occurs.
If you have multiple pre-existing conditions, look beyond the headline policy maximum.
Check these areas carefully:
Find out exactly how the policy defines a pre-existing condition.
If the plan offers acute-onset coverage, understand the requirements for an event to qualify.
Identify the maximum amount available for eligible treatment.
Look for language indicating whether a limit applies:
Some plans have different eligibility requirements or benefit limits based on the traveler’s age.
Pay particular attention to exclusions involving:
For travelers with diabetes, high blood pressure, cardiac disease, or multiple other pre-existing conditions, understanding how coverage limits work is especially important.
A visitor insurance policy may have a high overall policy maximum, but a much lower sub-limit for eligible acute-onset pre-existing condition treatment. Multiple conditions do not automatically mean that the sub-limit can be multiplied for each condition.
Before purchasing coverage, review the policy definitions, acute-onset provisions, sub-limits, age requirements, exclusions, deductibles, and claim conditions. If the policy language is unclear, confirm with the insurance provider or administrator how the applicable benefit limit works for multiple pre-existing conditions.

Travelers with multiple pre-existing medical conditions often have an important question when buying visitor.
Explore More
Air travel disruptions have become increasingly common, such as severe weather conditions, airport closures, airline.
Explore More
Traveling to the United States with a baby under one year old can be.
Explore More